FDNY Pension & 457(b) Calculator
Firefighters

Enter your start date, years and salary to see your own pension.

Put in your start date, your years and your salary to see what the pension and the Variable Supplement Fund pay you. Then get it written up as your Pension Printout, and bring it to a Free 15-Minute Call if you want one.

Updated Oct 2026: Tier 3 now pays 50% at 20; full escalation at 23 years and a 25-year bonus. What changed

Updated October 2026. For Tier 3 firefighters, a 20-year pension is now 50% of final average salary (Chapter 692 of 2025), and full escalation now comes at 23 years of service instead of 25 (Chapter 58 of 2026). The same 2026 law added a 25-year bonus for members with 25 or more years of uniformed service. This calculator includes all three. What changed

Hypothetical illustrations for education only. Not a prediction, recommendation, or guarantee. Your actual result will differ.

See what you get

New here? Watch the 2-minute walkthrough

Step 1 of 5 · Your dates and salary

Nothing is pre-filled, so the number you get is your own.

Want to see how it reads first?

Your QPP membership date, from your fund record. It sets your tier. Which date?

Use the date on your pension fund record, not your academy graduation. Built for firefighters and fire officers; EMTs and paramedics are in NYCERS on a different formula.

Pension tier: worked out from your hire date. Change it
Pension Tier
We auto-detect, but you can override if your fund record says otherwise.
$
Annual. Not sure yet? Use roughly your recent full-year pay. What counts for your tier

Tier 3: the average of your highest 3 consecutive years of pensionable pay (base + OT + longevity) for all Tier 3 members retiring on or after April 2024 (the April 2024 pension reform replaced the old 5-year average for post-2012 hires).

Tier 2: the greater of the final 12 months or the average of the highest 3 consecutive years, with anti-spiking caps.

A close figure is fine here; the Fund's certified calculation is the one that counts.

The month you're considering putting your papers in. How it's counted

We count your service to the first of that month, so a 20-, 23- or 25-year mark you reach later in the month shows from the month after.

No month in mind yet? Use your years of service instead
Tier 3 escalation phases in over the three years before your 23-year mark: none at 20 years or less, about a third at 21, two thirds at 22, full at 23. The May 2026 state budget (Chapter 58) moved this date down from 25. A standard 20-and-out retirement still receives no escalation.
Step 2 of 5 · Your pension, free
What you end up with in Step 5

Your Pension Printout. What the pension pays after federal tax, what the VSF adds, your 457(b) as a range rather than one number, and what your survivor options do to the cheque.

Your Pension at 20 vs Waiting
Estimated annual service pension on this date
$0
—
Educational estimate, not advice.
sirmiumcapital.com/fdny
Step 3 of 5 · Your pension plan

Your pension at 20 and 23 years, side by side, opens here once your number is in.

Your 20 and 23 years

The sample plan is built on made-up figures for one illustrative member. Your written plan works the same questions on your own numbers.

What moves your numberWhat your number means, and the inputs that move it most
What your number means

The inputs that move it most, in plain English.

The calculator gives you a number for a papers-in date. This section is about the decisions inside it: what builds it, which inputs move it most, and how to keep it. It updates live as you change the dates above, and it is a hypothetical illustration built only on the figures you entered, not a projection and not advice.

These sentences describe the sample dates above. Change the inputs in the calculator and they describe you.

The inputs that move this number most

Each line changes one input and holds the rest, before taxes. Real decisions move several at once, which is what a planning conversation is for.

The link keeps your numbers in your browser's address bar only. We do not receive or store them, and nothing is emailed. Anyone you send the link to will see the numbers you entered.

Walk through these levers in 15 minutes

Fee-only · Fiduciary · FDNY-specialized · Free, no obligation

These sentences and figures are hypothetical illustrations based only on the numbers entered above. They are one of several possible outcomes, not a prediction. You can change the inputs at any time to see how the picture shifts.

This is educational information, not investment, tax, or legal advice, not a recommendation to retire, keep working, or pick a date, and not a guarantee. Sirmium Capital LLC is a New York state-registered investment adviser and is not registered with the SEC. Using this tool does not create an advisory relationship. Confirm your figures with the NYC Fire Pension Fund and, for tax questions, a qualified tax professional.

Your number, line by lineTier, service, escalation, and the things to weigh
The 2025 change most members haven't heard

—

Tier (from your date)—
Service on this date—
Pension as % of FAS (current law)—
25-year longevity bonus (included)—
Inflation escalation locked in—
Your full-escalation (23-yr) date—
Things to weigh

—

Your papers-in date sets your FAS window AND how much inflation protection you lock in. Worth modeling before you pick it.

Two bills would move this dateWhat changed in May 2026, and the bill that could change it again

Two bills would move this date

Full escalation, the inflation raise on your pension, now comes at 23 years. The May 2026 state budget (Chapter 58 of 2026) moved it down from 25, and it is in effect now. A bill in the Senate committee, S9203, would move it again, to the day you become eligible to retire. That one is not law and not something to plan around. We read it every day. Leave your email and you will hear if it moves.

Only when a bill moves. Nothing else. When you send your email, the figures you typed are saved with it, so we can prepare for a call. They're never put in an automated email. You can stop the emails in one click.

Step 4 of 5 · Your retirement plan and accounts (optional)

Skip to Step 5: your printout

Next: turn your pension into a retirement plan

Your figure above shows what the pension pays. This part plans the life around it: when you go, what you'll live on, your 457(b), your family, and the work you'll do after the job. If you'll take another job after the FDNY, security, the trades or anything else, put its pay in number 5. Each answer is written into the printout you get in Step 5.

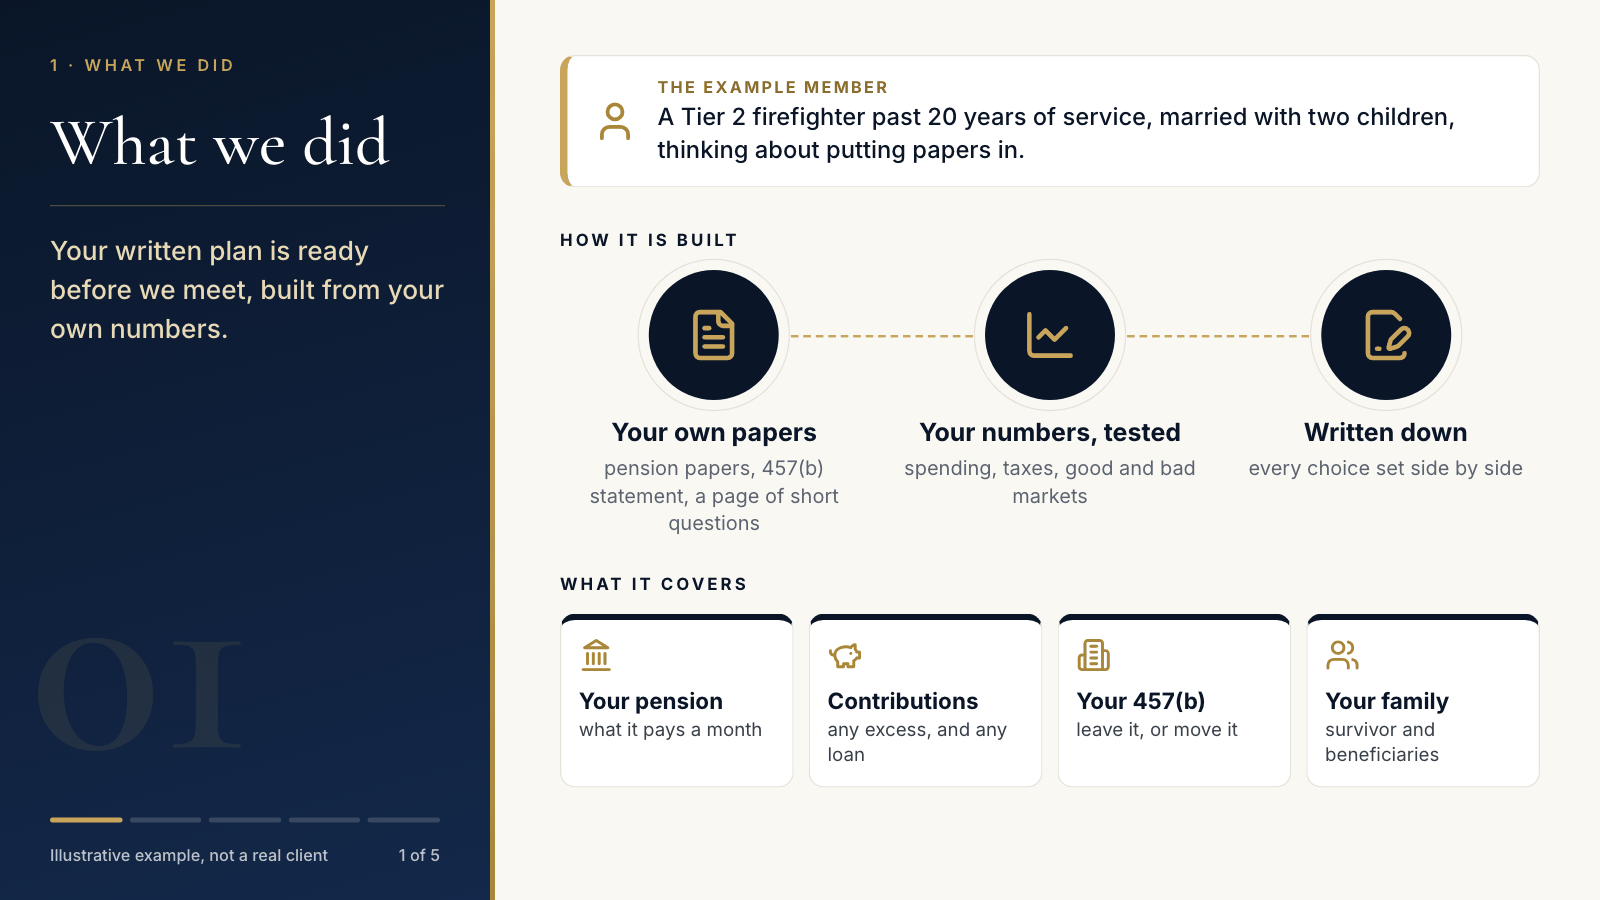
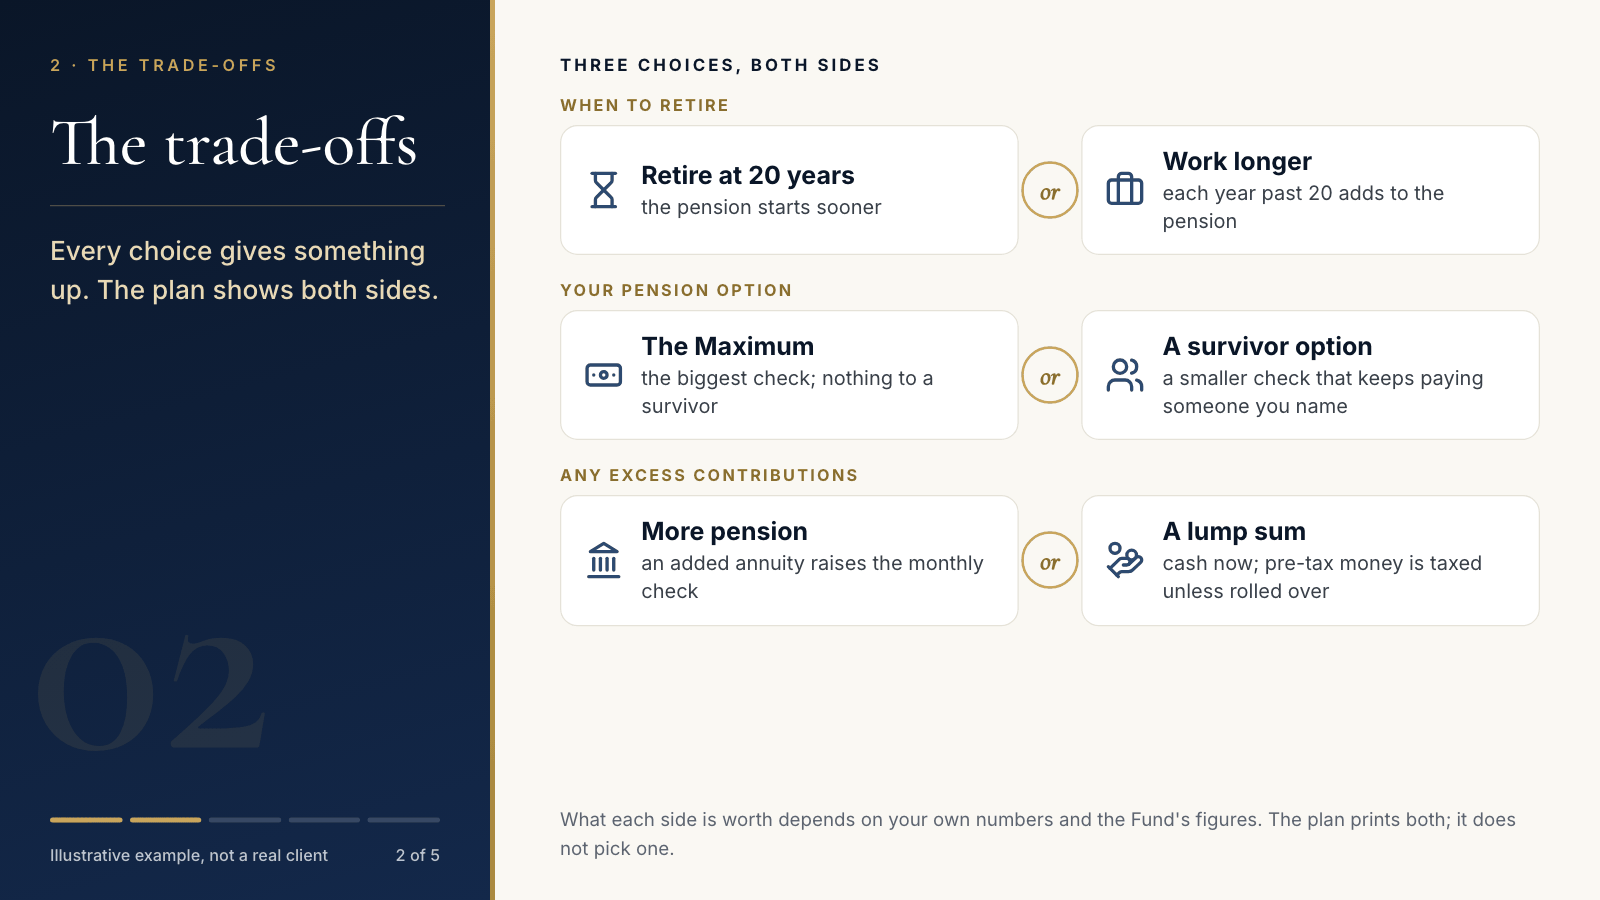
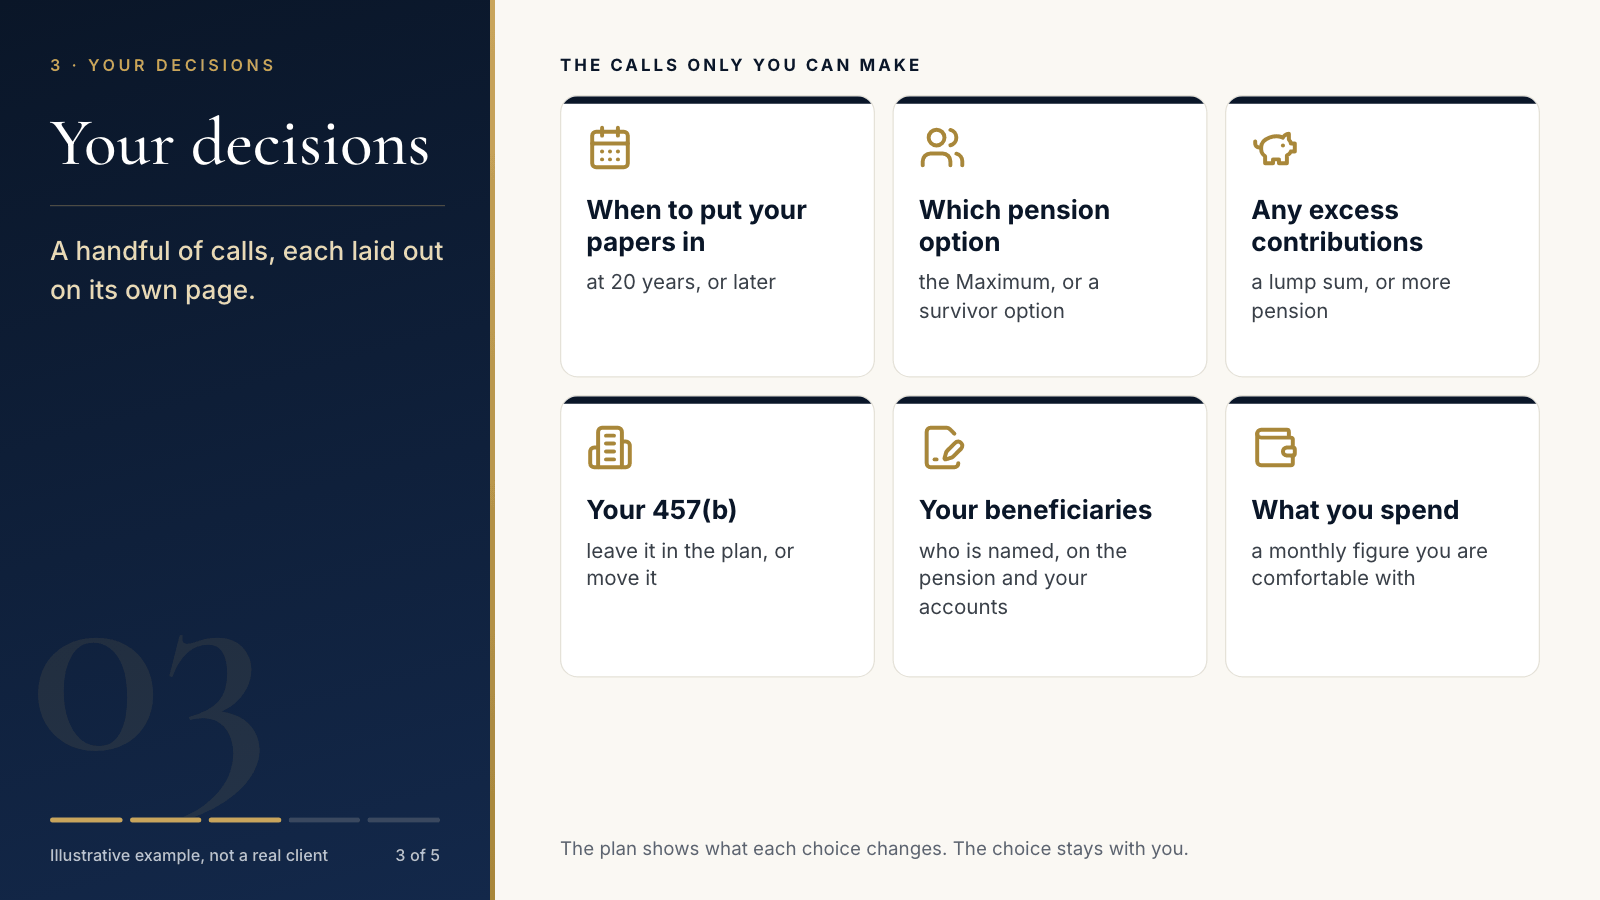
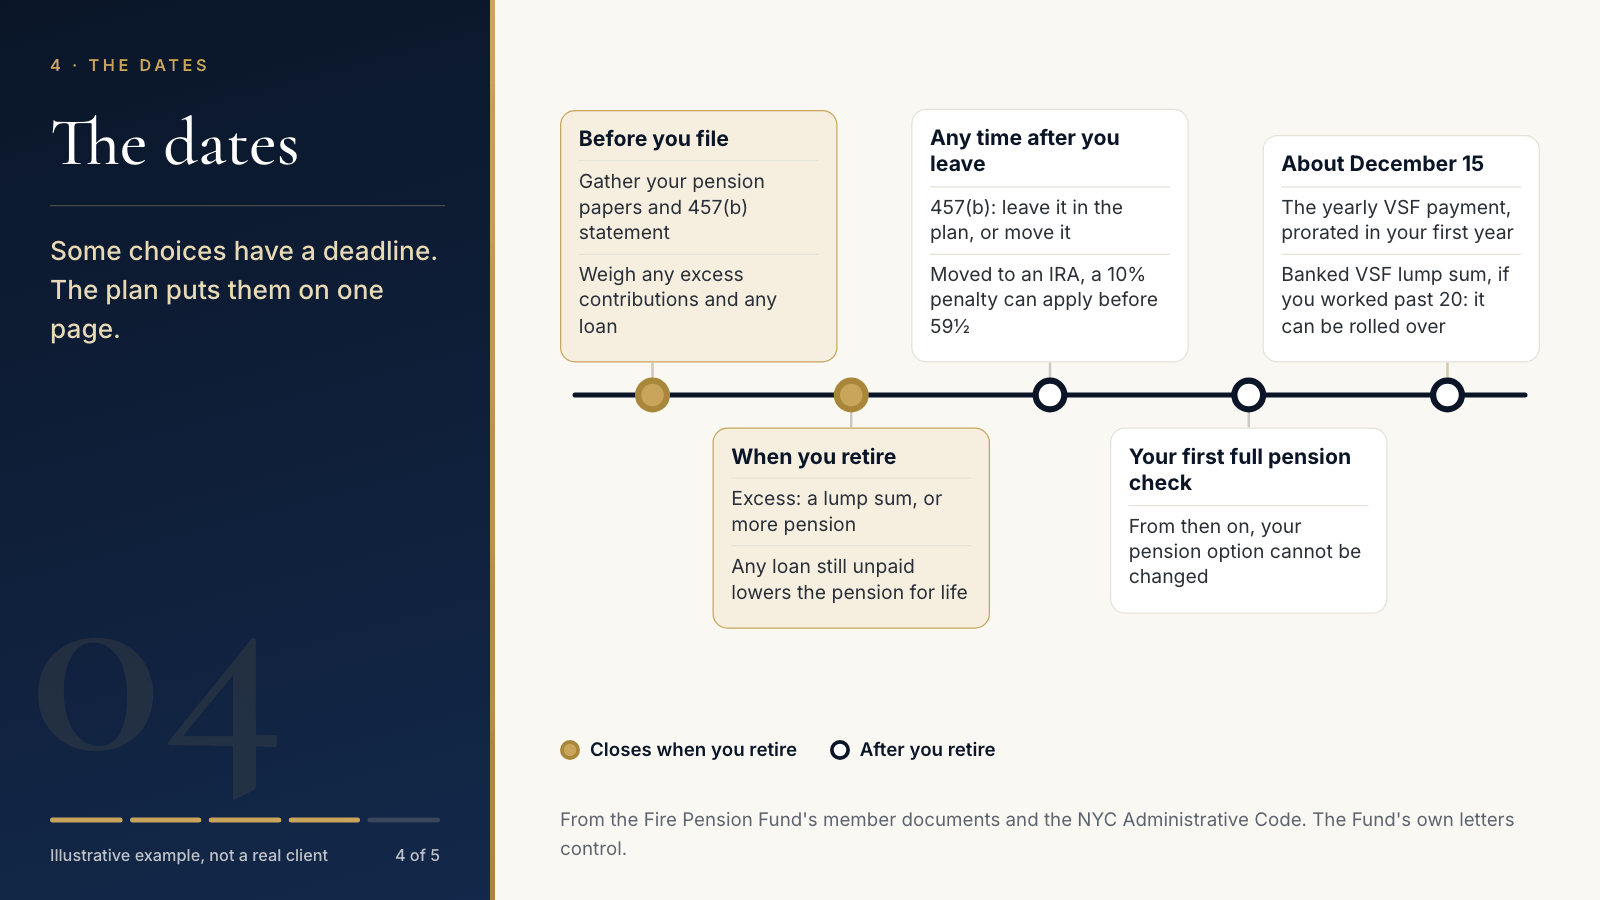
Sample of the finished plan, five sentences in the member's own words: papers in during March 2031, living on $7,500 a month, the 457(b) balance and contributions, someone depending on the income, and second-career pay of $60,000 a year for 10 years.
This is what you get: a sample of the finished plan in your printout, for an illustrative firefighter, not a real client.

What you do here: finish five short sentences about your own retirement. The first comes from the papers-in date you already set in Step 1.

What you get: each sentence written into your Pension Printout with the numbers worked out underneath, and anything you can't settle listed as a question for the free 15-minute call.

Nothing here is a recommendation. These are your calls, in your words.

0 of 5 settled
  1. Set as your papers-in date in Step 1.

  2. $
  3. $

    Your balance goes in the Your 457(b) tool, under Go deeper.

  4. Your 457(b) draw and Social Security go in the Your retirement paycheck tool, under Go deeper. Your job after the FDNY goes here:

    $
    A public benefit corporation means the MTA, Health + Hospitals, the Port Authority and the like. "State, City or school" covers New York State, the City of New York and a school district. It matters because a New York public pay cheque and a private one land differently against your pension under Section 212.
Which of these do you have? (tick any)

If you ask for your pension guide, these go with the request, so we can prepare.

Step 5 of 5 · Your printout, then a call

Your age turns this into your Pension Printout

From 25 years of service, a share of your rank's top pay is added to the salary your pension is figured on (Chapter 58 of 2026). Above Deputy Chief, pick Deputy Chief: the estimate will run low, not high.
Make it more exact (optional)

None of this is needed to get your printout.

This turns the before-tax figure into take-home. Single and married are taxed very differently, so the page does not guess it.

This is what you get: your pension a year, the VSF where it applies, the tax on it, what lands each month, and your 457(b) as a range.

Sample Pension Printout for an illustrative firefighter: pension a year, the Variable Supplements Fund, the total before tax, federal tax, State and City tax at zero, and what lands each month.
Sample for an illustrative firefighter, not a real client. Tap to see it full size.

Rather talk it through? Free 15-Minute Call with Eslyn Hernandez, nothing to sign.

Your tier, salary and service come from Step 1. Anything you have not filled in is left out of the printout rather than filled in with a typical number. Everything is worked out on this device from what you type. Your exact figures are only sent if you leave an email. We keep broad, anonymous ranges (like tier and a salary range) to improve the calculator.

What this covers, and what it will not do

It covers service retirement at twenty or more years of credited service. Below twenty it gives no pension figure at all, because the rate a tool would need for a deferred benefit is an estimate rather than a figure the Fund has certified, and we would rather print nothing than a number we cannot stand behind. It also leaves out the Fund's term for service transferred in from another system and the pension based on your ITHP contributions, neither of which can be worked out from what you entered, and both of which would add to the figure rather than reduce it.

Your numbers
Pension on this date—
Escalation locked in—

The questions this calculator cannot answer

An estimate is a fact, and a fact does not need discussing. These do: whether to put your papers in at twenty or stay, what happens to the cheque if something happens to you, whether your 457(b) should move when you leave, and whether a WTC notice belongs in your file before the window closes. Bring whichever of those is yours to a free 15-minute call with our team. No products, no commissions, no obligation.

Bring my questions to the free 15 minutes

Built on the real FDNY rules: the NYC Fire Pension Fund’s Tier 2 and Tier 3 provisions (Tier 3 under RSSL Article 14, incl. Chapter 692 of 2025), the NY $20,000 exclusion, and 2026 IRS figures.

Know your number, but not sure how to invest it? Take the 2-minute risk profile →

Go deeper

Nothing here is needed for your pension figure or your printout. The tools work one piece through on its own; the reading below them is the reference behind the figures.

Tools

Your retirement paycheckPension, VSF, 457(b) draw, Social Security and tax, a month
Your Pension Tier
Tier sets how inflation treats your pension. Tier 3 escalation is the lesser of CPI or 3% a year, paid in full from 23 years of credited service and in part between 20 and 23; Tier 1/2 get a partial COLA on the first ~$18,000 only. Tier 3 Original, Modified and Enhanced all sit under Tier 3 here, because in this worksheet only the inflation treatment differs and it is the same for all three. Step 1 splits them out, where the difference does change the math. If you're not sure, your Fire Pension Fund estimate or membership date tells you. This tool does not compute the tier formula.

Years of credited service comes from , at the top.

$
Annual, before taxes. Use the number on your Fire Pension Fund estimate. This tool does not compute the tier formula.
VSF is generally a fixed $12,000/yr for members who retire for service with 20+ years on a QPP service pension. Not for disability or vested-deferred retirees. It is flat (no COLA, no escalation), so it loses purchasing power every year. Eligibility and amount are set by the fund. Only include it if your fund confirms you qualify. (Before age 62 the VSF is reduced by a COLA offset; this tool shows the full amount.)
$
$
About that Social Security number FDNY work is covered by Social Security, so your FDNY pay counts toward your own benefit, along with any other covered work. The WEP and GPO offsets never applied to FDNY service, so their repeal in January 2025 does not raise a benefit based on it. Check your real number at ssa.gov/myaccount. Educational note, not advice.
NY does not tax your FDNY pension or VSF; 457(b) withdrawals are NY-taxable beyond a $20,000 exclusion if you are 59½+. Florida has no state income tax. New Jersey exempts Social Security and, at 62+, may exempt pension/457 income under its Retirement Income Exclusion when total New Jersey gross income is within the limit ($100,000 for all filers, with a phase-out to $150,000; simplified here). Other states vary.
A scenario you choose, not a forecast. Used only to show what today's dollars are worth later. The long-run average has been roughly 2–3%.
Your Estimated Paycheck
Estimated pre-Social-Security monthly income
$0
—
Educational estimate, not advice.
sirmiumcapital.com/fdny
FDNY pension (annual, gross)—
VSF (annual)—
457(b) withdrawal (annual)—
Federal tax (rough est.)—
State tax (rough est.)—
Pre-SS net (monthly)—
Once SS starts: net (monthly)—
What inflation does to your check
In today's dollars, this stack is worth
—
—
Inflation-protected — Partly protected — Not protected —
—
Things to weigh

—

The $35,000 cap may become $65,000

There is a $35,000 limit on what you can earn in a New York public service job after you retire before it affects your pension. A bill raising it to $65,000 from 2027 passed the Senate 59 to 0, then went back to committee. It is not law yet. We check it every day. Leave your email and you will hear when it moves.

Only when a bill moves. Nothing else. When you send your email, the figures you typed are saved with it, so we can prepare for a call. They're never put in an automated email. You can stop the emails in one click.

The survivor decision is not in these calculators, and it cannot be. Option costs are certified by the NYC Office of the Actuary and are not published, so no honest figure can be shown here. What can be set out is the mechanics, the option names in each tier, and the election deadline, which is not the same for Tier 3 Enhanced as it is for Tier 1 and Tier 2: FDNY survivor options.

Your 457(b)Keep it or roll it when you leave, and the Roth conversion window

Keep it or roll it

Loaded with a typical firefighter's numbers. Change what you know and leave the rest. You do not need exact figures, so it takes about 30 seconds.

$
$
Total dollars you'd likely withdraw between separating and age 59½. Capped at your balance.
What the Numbers Say
What's at stake
0 yrs
of penalty-free access before 59½.
Educational estimate, not advice.
sirmiumcapital.com/fdny
Max 10% penalty an IRA would charge on early withdrawals (one-time)—
457(b) value in horizon —
IRA value in horizon —
Fee difference over horizon (future $, whole balance)—
How the balance splits against what you said you would need

—

Things to weigh

—

The penalty-free 457(b) window closes for good the day you roll. Worth a careful look before you decide.

We read the pension bills so you do not have to

Full escalation, the inflation raise on your pension, now comes at 23 years: the May 2026 state budget (Chapter 58) moved it down from 25. The biggest FDNY bill still pending, S9203 / A10254, would move it again, to the day you become eligible to retire. It is sitting in committee and is not law. We check New York pension bills every day. Leave your email and you will hear when it moves.

Only when a bill moves. Nothing else. When you send your email, the figures you typed are saved with it, so we can prepare for a call. They're never put in an automated email. You can stop the emails in one click.

The Roth conversion window

$
Your federal taxable income (after the standard deduction). Your pension is the usual main piece. NYC/FDNY pension is not taxed by NY, but it is taxable on your federal return, so it counts here.
$
Your traditional 457(b) and/or traditional IRA dollars. Roth balances do not belong here.
75 if born in 1960 or later, which covers nearly every serving member. 73 only if born 1951-1959 (SECURE 2.0 sec. 107).
Your Conversion Window
Hypothetical total you could move to Roth before RMDs
$0
—
Educational estimate, not advice. Not a recommendation to convert.
sirmiumcapital.com/fdny
Window length (low-income years before RMDs)—
Room in your target bracket this year—
Annual conversion headroom (lowest of the ceilings)—
What's holding the headroom—
Rough federal tax on one full-headroom year—
Things to weigh

—

Every year that passes is one fewer low-tax year before RMDs begin.

We read the pension bills so you do not have to

Full escalation, the inflation raise on your pension, now comes at 23 years: the May 2026 state budget (Chapter 58) moved it down from 25. The biggest FDNY bill still pending, S9203 / A10254, would move it again, to the day you become eligible to retire. It is sitting in committee and is not law. We check New York pension bills every day. Leave your email and you will hear when it moves.

Only when a bill moves. Nothing else. When you send your email, the figures you typed are saved with it, so we can prepare for a call. They're never put in an automated email. You can stop the emails in one click.

Did you work at the World Trade Center site or in the recovery operation?

If yes, this opens what a WTC disability pension could pay on your plan, and the Notice of Participation deadline.

Important: These calculators are hypothetical illustrations for education only. They are not investment, tax, or legal advice, not a recommendation, and not a guarantee. Your actual result will differ. If you later become a client and roll over assets, Sirmium may earn advisory fees on those assets; weigh that when reading the 457(b) tool.

How these figures are calculated, and the sources behind them

Figures use general 2026 federal and NYC figures, current as of July 2026 (IRS Rev. Proc. 2025-32; NYC Fire Pension Fund / Office of the Actuary; CMS), and do not reflect credits, other income, NIIT, AMT, capital-gains stacking, your state return, market ups and downs, or your full balance sheet. They are not tax advice or tax preparation. RMD age, IRMAA thresholds, VSF eligibility, and the NYC COLA can change and depend on your situation. Registration does not imply a certain level of skill or training. Confirm specifics with the NYC Fire Pension Fund, the NYC Deferred Compensation Plan, and a qualified tax professional before acting.

Reading

From your Pension Printout to a written plan, in five steps

  1. 1Run the calculator. Your Pension Printout shows what the pension pays a month and what each survivor option does. It's free, and you don't need to give an email to see your figure.
  2. 2Get your free pension guide. Ask for it under your pension figure. Within one business day Eslyn Hernandez emails you a guide built on the numbers you entered: a short PDF, a video that walks you through it, and the key points as slides.
  3. 3Ask for your written plan. If you want the whole picture, answer one page of short questions and send your latest Fire Pension Fund statement. We build it before we talk: your pension, your 457(b), protecting your family, your job after the FDNY, and what you can spend, set side by side with what we recommend, plus a video that walks you through it.
  4. 4Walk through it with us. A call with William Harrison, our adviser, and Eslyn Hernandez. If you then want help moving money, we fill in the forms and you sign.
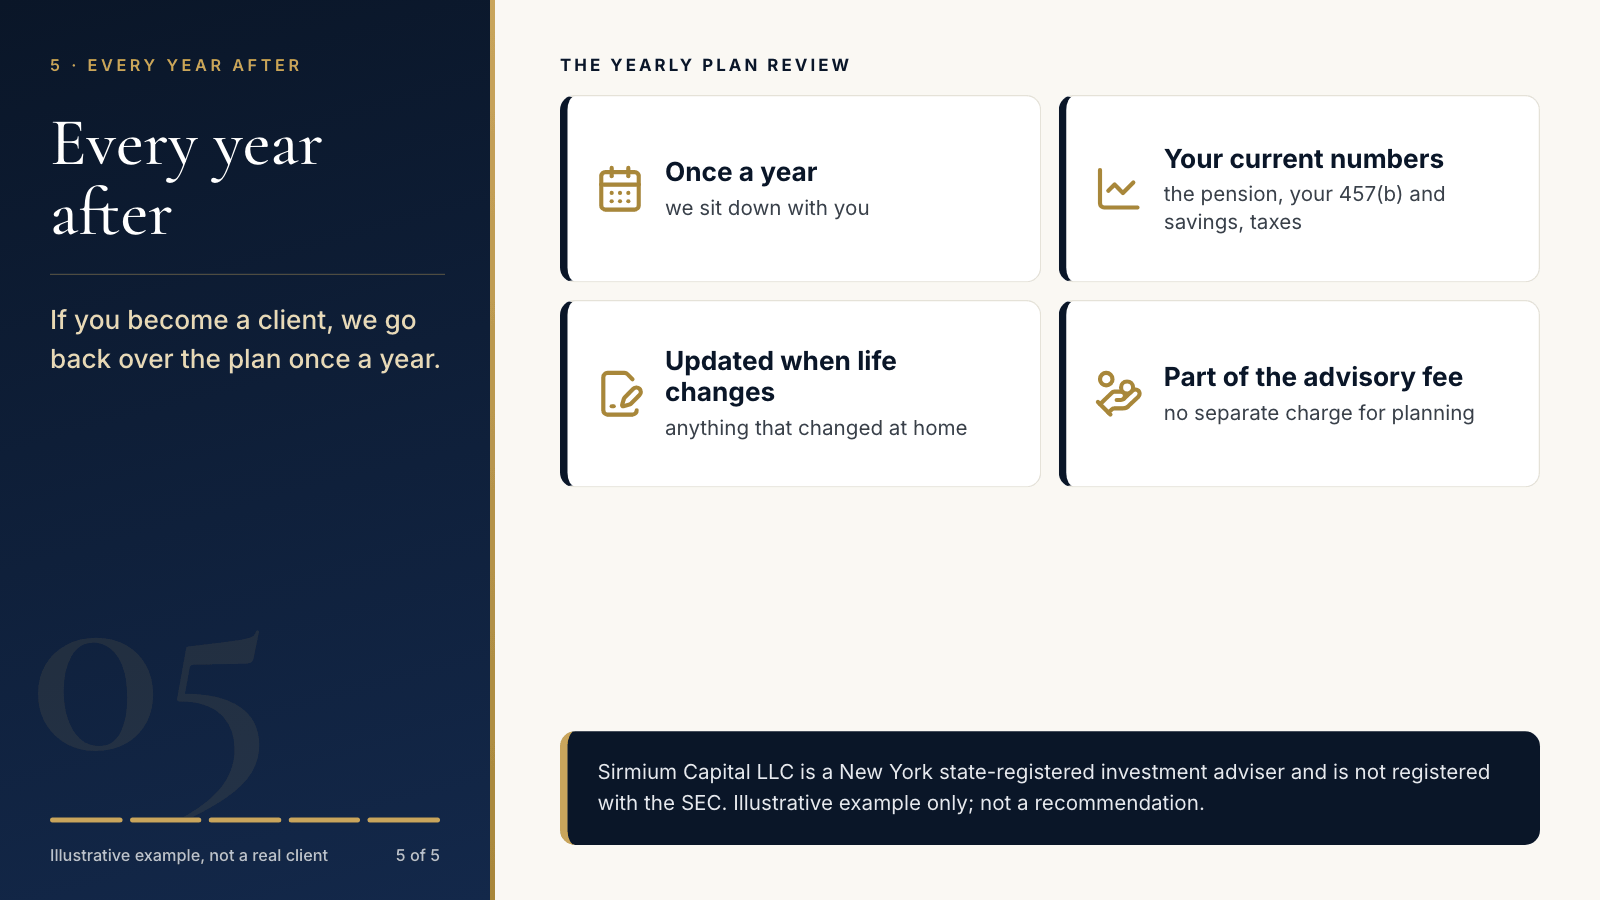
  5. 5Every year after, if you become a client. Once a year we sit down with you and go back over the plan with your current numbers: what the pension pays now, where your 457(b) and savings stand, taxes, and anything that changed at home. When something has moved, the plan gets updated. It's part of the advisory fee, with no separate charge for planning.

Why plan, and why with an adviser. The calculator answers one question well: what the pension pays. Retirement asks several more, most of them once, around the day you file, and each one changes the others. Moving the 457(b) changes when you can touch it without a penalty. The survivor option changes what your family has if you go first. Pay from a second job changes how much you need to draw. A plan puts all of it on one page before you file, so you're choosing with the whole picture rather than one box at a time. An adviser adds a second set of eyes on those choices, help with the Fund's paperwork, and a plan that gets re-run every year instead of going stale in a drawer.

What it costs. Nothing to plan, and no obligation. If you then want us to manage the money, the advisory fee and what it includes are set out in our Form ADV Part 2A. How working with us works.

See a sample written plan (PDF) · Start with the calculator

The sample is an illustrative firefighter, not a real client. Its figures are examples under stated assumptions; a projection is not a promise.

How much does an FDNY pension actually pay after 20 years?

On a $120,000 final average salary, a Tier 3 Original member (hired 2010, retiring at 20 years) draws about $60,000/yr (roughly $5,000/month) before tax, plus the fixed $12,000/yr Variable Supplement Fund on top. This is a worked example on this hire date and salary, not your number — enter your own membership date, FAS and retirement date in the calculator above to see yours. This is general educational information, not personalized advice.

Should I roll over my NYC 457(b) when I retire from FDNY?

The NYC 457(b) (the NYC Deferred Compensation Plan, or NYCDCP) and an IRA differ most before age 59½. Once you leave City service, money you take out of the NYC 457(b) carries no 10% early-withdrawal penalty, at any age. Money rolled into an IRA generally loses that status and can become subject to the 10% penalty on withdrawals before 59½, unless an exception such as a 72(t)/SEPP schedule applies. Which one fits depends on when you expect to need the money and what each account costs you. Sirmium models the early-access window against the rollover decision for FDNY families. This is general educational information, not personalized advice.

Your pension is one number. Retirement is six decisions.

A Financial Plan puts your own numbers on each one. Whether one is worth it for you is a question for the Free 15-Minute Call.

  1. When you file your papers: 20 years for a service pension, 23 for the full yearly inflation raise on a Tier 3 pension, and 25 for the longevity bonus.
  2. Your banked VSF: the $12,000 a year for each year you work past 20, paid as a lump sum when you leave, and where it can go. Disability retirees do not get it.
  3. Your extra contributions (Tier 2): take them as cash or as a bigger pension, and whether to take a pension loan, which cuts the pension for life.
  4. Your 457: where it sits after you leave, and the penalty rule that changes if it moves.
  5. Your union annuity (UFA or UFOA): the account the City pays into and you invest yourself. What you can do with it at retirement is a question for the call.
  6. Your pension option: the maximum, or a survivor option, and who that protects. A survivor gets half of any cost-of-living raise.

Sources: the 23-year escalation date, RSSL 510(b)(2-a), added by Chapter 58 of the Laws of 2026, Part ZZ; the longevity bonus, NYC Administrative Code 15-110.1 (Chapter 58 of 2026, Part AAA); the VSF and the banked VSF, NYC Administrative Code 13-385 and Chapter 216 of the Laws of 2002; extra contributions, loans and ITHP, the FDNY Pension Manual, Tier 1 and 2 chapter, and the NYC Fire Pension Funds FY2025 financial statements; Tier 3 contributions, RSSL 517; the union annuity, the City's UFA and fire officers contracts; pension options, the FDNY Tier 3 Enhanced plan description (July 2022) and the Tier 1 and 2 manual; the 457 penalty rule, IRC 72(t).

Your Pension Is Powerful. But It Has Rules Nobody Explains.

Tier 2 vs. Tier 3 pension structures determine your multiplier, your Variable Supplement Fund timing, and when it makes sense to retire. The VSF (the Variable Supplement Fund) pays you a fixed $12,000 a year in retirement, and working past your 20-year mark banks an added lump sum, but the timing of your retirement date affects what you collect and when.

Your NYC 457(b) deferred comp has a unique advantage most advisors miss: you can withdraw it penalty-free before age 59½ when you separate from service. Roll it into an IRA and that window closes permanently. We check this before recommending anything. See the 457(b) withdrawal rules and what a rollover would cost you →

If you have any student loans (firefighters who went back to school), PSLF may forgive your remaining balance after 10 years of service. One wrong move (like refinancing to a private lender) eliminates that eligibility forever.

FDNY Planning Areas

  • Tier 2 vs. Tier 3 pension: retirement date optimization
  • VSF timing: how your retirement date affects supplement payments
  • NYC 457(b) rollover decision: keep penalty-free access or roll to IRA
  • VSF "Banked Variable": what working past your 20-year mark adds to your lump sum
  • PSLF for firefighters with student loans

Why Your Pension, Your 457(b), and Your Taxes Are One Decision

A firefighter hitting 20 years is usually in the mid-40s. The choice on the table looks like one question, file now or stay, but it moves three sets of numbers at once. None of them can be answered alone.

The retirement piece. The pension at 20 is a lifetime floor, fixed by statute, and every year past 20 adds to it. But retire in your mid-40s and you will likely be retired longer than you worked, with a 15-to-25-year gap before Social Security starts. Something has to bridge those years, and the only account you fully control is the 457(b).

The tax piece. The pension is New York State and City tax-exempt but federally taxable. The 457(b) is where the tax decision lives: kept at the DCP, it is penalty-free at any age once you separate. Rolled to an IRA, the same dollar touched before 59½ can cost 10 percent. And the low-bracket years between your last FDNY paycheck and Social Security are among the cheapest Roth conversion years you may ever see. A WTC or accident disability pension changes the federal tax character entirely, which reorders which account gets drawn first; the specifics of your situation belong with a tax professional.

The investment piece. A pension plus the $12,000 VSF works like a large bond position with your name on it, so your 457(b) and IRA should not be invested like a civilian 45-year-old's portfolio. The floor is already built. But those same dollars have two conflicting jobs: paying the bridge years now and growing for the decades after. That is an allocation question, not a product question.

Every answer moves the others. Stay two more years and the pension rises, which fills more of your tax bracket, which shrinks the conversion window and changes what the 457(b) has to do and when you can spend it. The Pension Fund answers the pension question, the IRS answers the tax question, and the DCP answers the account question. Nobody answers across the seams, and the seams are where retirements are won or lost.

The calculator above asks these questions. Run them on your own numbers, then bring what you see to a free 15-minute call. Planning is free; specific recommendations come from William Harrison, the firm's investment adviser.

Get Your Free FDNY Retirement Blueprint

The five decisions that move the most money at separation: the 457(b), your retirement paycheck, the Roth conversion window, pension at 20 vs 25, and the 9/11/WTC deadline. Built for FDNY retirees, and made to read alongside the calculator above.

Download the free Blueprint (PDF) Download the free checklist (PDF)

Sirmium Capital LLC is a New York state-registered investment adviser and is not registered with the SEC. Educational purposes only. Not personalized financial advice.

What's Inside:

  • Tier 2 vs. Tier 3: the retirement multiplier difference
  • VSF payment schedule and when to time your retirement
  • Why rolling your 457(b) early can cost you penalty-free access
  • PSLF eligibility for fire service members

FDNY Planning Resources

Free book

The FDNY Pension Book, 2027 Edition

Fifty percent at twenty for Tier 3, full escalation at twenty-three, and the new twenty-five-year raise, with every number traced to the law it came from.

Get the free PDF →
Calculator

What a 457(b) rollover would cost you

A governmental 457(b) is the only account you can tap at any age after you leave the job without the 10% penalty. Roll it to an IRA and that stops. Put in your separation age and balance and see the number, plus your 2026 contribution limits across the 457 and the 401(k).

Open the 457(b) calculator →
Calendar

2026 NYC pension payment dates

New York City pension systems pay on the last calendar day of the month and roll forward when that day is a weekend. Four of the twelve 2026 payments therefore land in the following month. Printable calendar with every date.

See the 2026 pension payment calendar →
Watch

The Five Decisions of an FDNY Retirement

A short, plain-English walk through the five choices that set your retirement income for life: pension timing, the VSF, your 457(b), the Roth window, and the 9/11 WTC deadline. Education only, no obligation.

Research Letters

Calm, sourced letters from our CIO

Short, plain-English research you can read and forward to a friend on the job. Educational information only, not legal or tax advice.

Article

FDNY 457(b) in Retirement: What Most Members Get Wrong

Guide

FDNY 457(b) Rollover Decision Guide

Guide

The FDNY Retirement Blueprint

The whole picture in one written guide: your pension, the 457(b), the bridge to Social Security, and the 9/11/WTC filing deadline.

Article

FDNY Retirement Timing: Retire at 20 vs. Stay for Full Value

Article

FDNY Tier 2 vs. Tier 3 Pension Explained

Article

FDNY Pension Buyback 2026: Is It Worth It?

Will’s Q3 2026 letter: What AI Can’t Buy YouOur CIO’s quarterly letter, free to read, with a 3-minute video.

FAQs

Common FDNY Financial Questions

A NYC Fire Department Pension Fund service retirement pays 50% of Final Average Salary (FAS) at 20 years of service. For Tier 2 (firefighters hired before 7/1/2009), each year worked past 20 adds 1/60 of total earnings after the twentieth anniversary, about 1.67% of FAS a year when those earnings track FAS, and FAS is based on final salary with a 3-year anti-spiking limit. For Tier 3 (RSSL Article 14, hired on/after 7/1/2009), Chapter 692 of 2025 raised the benefit at 20 years from 42% to 50% of FAS (previously 50% required 22 years; Tier 3 members could always retire at 20), and FAS is the highest-3-consecutive-years average for all Tier 3 members retiring on or after April 2024 (the April 2024 pension reform replaced the 5-year average that had applied to post-2012 hires). Since May 26, 2026, a member of either tier who retires with 25 or more years of uniformed service also has 5% of the top pay for their rank, plus 1% for each year past 25 (15% at most), added to the salary the pension is figured on (Chapter 58 of 2026). Tier 3 allowances are reduced at age 62 by 50% of the primary Social Security benefit. Sirmium models these tier, hire-date, and offset variables for FDNY families on its free FDNY pension calculator.
The FDNY Firefighters' Variable Supplement Fund (VSF) pays a flat $12,000 per year to members who retire on a service retirement with 20 or more years of uniformed service (NYC Administrative Code §13-385, the payment section; §13-383 establishes the fund but sets no amount — fire officers have the same $12,000 under §13-395); it is a fixed amount with no COLA. Vested or disability retirees are not eligible. If you receive a pension COLA before age 62, that COLA offsets the VSF dollar-for-dollar until you turn 62. This matters for the 20-and-out path: a firefighter who retires in their forties can become COLA-eligible at 55 once retired ten years (or at 62 after five), and the offset applies from then until 62. Confirm your own COLA start date with the NYC Fire Pension Fund. Sirmium models VSF timing into the first-year cash-flow plan for FDNY retirees.

Ready to Begin?

15 Minutes.
Just Honest Answers.

Book a free 15-minute call. We'll walk through your pension tier, 457(b) situation, and answer whatever you're thinking about.

Bring these and 15 minutes is plenty

Your 457(b)/NYCDCP balance and the fund it's in  ·  your pension tier and monthly estimate (and VSF eligibility)  ·  other accounts: IRA, Roth, brokerage, yours and your spouse's  ·  the monthly income you'll want in retirement. Ballpark is fine. Come anyway and we'll point you to exactly what to pull.

Book a Free 15-Min Call

Reviewed as of July 2026. Verified against the NYC Fire Pension Fund plan documents, the Retirement and Social Security Law, and 2026 IRS figures.

Sources: Chapter 692 of 2025 (Senate S4727) · RSSL §511 (age-62 Social Security offset) · NYC Admin Code §13-385 (VSF payment of supplemental benefits; §13-395 for fire officers) · IRS 2026 inflation adjustments (Rev. Proc. 2025-32). Rules and figures change; confirm your own situation with the NYC Fire Pension Fund and, for tax questions, your tax professional.

How we keep this current. Pension rules change, and a lot of what is online is out of date. We track New York pension legislation and the funds’ own publications, and we update these tools when the law moves. When Chapter 692 of 2025 raised the Tier 3 pension at 20 years from 42% to 50% of final average salary, we updated the calculator to match.